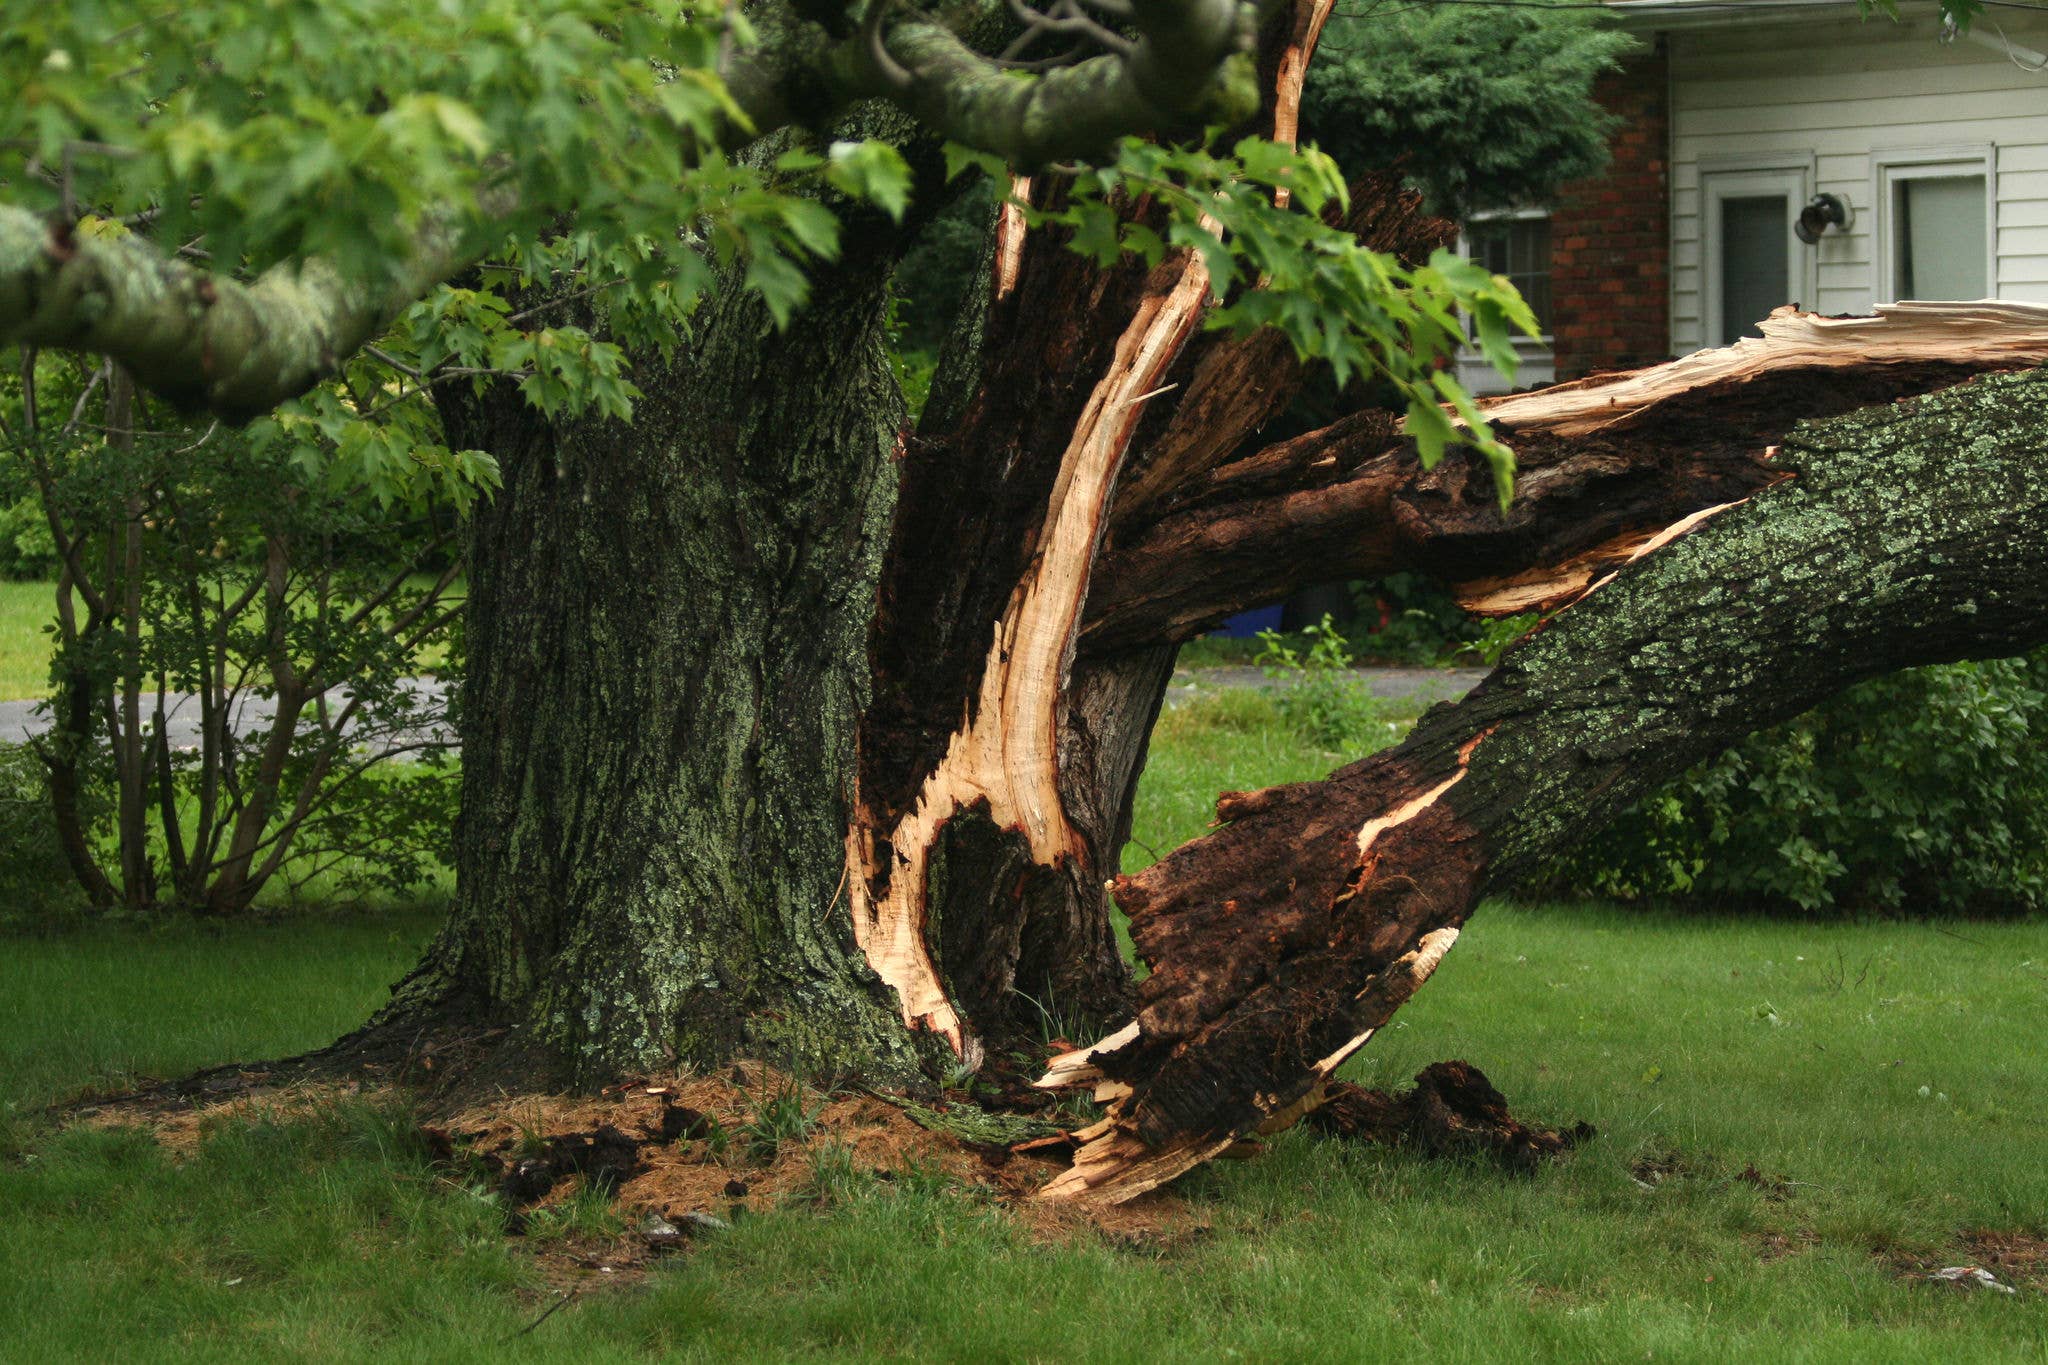
Does Homeowners Insurance Cover Fallen Trees?
If a tree falls due to a covered peril, your homeowner's insurance will most likely cover the costs. Learn about what services are covered and more.

by COUNTRY Financial
Home insurance typically protects your house from storm-related damage. The amount of coverage depends on your policy, and some events, like floods, are not covered unless you purchase additional coverage.
But for damage caused by wind, hail, lightning or the other covered perils below, your standard home insurance policy generally protects your home and personal belongings.
Find out more about home insurance.
Find out more about home insurance.
Homeowners insurance typically covers physical damage, water damage, and losses to personal belongings caused by storms.
Physical damage to your home’s structure is protected by two coverages in your home insurance policy: dwelling coverage and other structures coverage.
Dwelling coverage protects the physical structure of your main house, the home you live in. Other structures coverage does the same for other buildings on your property, like barns, sheds and gazebos.
Home insurance coverage will generally cover severe weather damage caused by:
Once you pay your home insurance deductible, your dwelling coverage and other structures coverage will help pay for the remainder of the damage (up to coverage limits).
Home insurance will generally cover water damage caused by a storm. If severe weather breaches your home and exposes it to rainwater, dwelling coverage (or other structures coverage) can help pay for the resulting water damage to walls, floors and other interior structures. The same is true in the event of burst pipes during a hard winter freeze.
Standard home insurance will not cover flood damage. Homeowners need separate flood insurance for flood damage.
Personal belongings inside your home can also be damaged by a storm, including furniture, electronics and clothing. Most home insurance policies include personal property protection, which pays to repair or replace damaged or destroyed items in your home, depending on your policy.
When it comes to storm damage, several types of damage fall outside what standard home insurance covers, including flood damage, earthquake damage and sewer or drain backup.
Not every storm causes major damage, but keeping your home well maintained reduces the risk of damage from smaller storms.
Here's a list of things to prepare your home for severe weather:
Storms are an inevitable part of life. The destruction they cause can greatly disturb our lives.
But when you're armed with knowledge and preparation, a storm can inconvenience your family rather than devastate it.
If you'd like to know more about how homeowners insurance covers storm damage, talk to your insurance agent. They can help you determine how much coverage you need and answer any questions.
Wind damage, including damage from tornadoes and high winds, is covered under your standard dwelling and other structures coverage. Flood damage is not covered by standard homeowners insurance and requires separate flood insurance, such as coverage through the National Flood Insurance Program.
It depends on your policy and location. Many storm damage claims fall under your standard homeowners insurance deductible, but separate wind/hail deductibles are increasingly common, and homes in coastal areas may carry a distinct named storm or hurricane deductible. Check your policy declarations page or ask your representative to confirm which deductibles apply to your coverage.
Contact your COUNTRY Financial insurance agent, who can help you understand your coverage and file a claim if your home has storm damage.
Published 9-18-26
If a tree falls due to a covered peril, your homeowner's insurance will most likely cover the costs. Learn about what services are covered and more.

Home insurance typically covers fire damage to your home and personal belongings through your policy. Learn about what type of fires are covered and more.

If you carry comprehensive coverage, hail damage should be covered by your auto insurance policy. Learn about liability coverages, storm damages, and more.
Start a quote or call us at 866-COUNTRY (866-268-6879). Find out more about home insurance.
Contact your rep or call us at 866-COUNTRY (866-268-6879). Find out more about home insurance.
Home insurance policies issued by COUNTRY Mutual Insurance Company®, COUNTRY Casualty Insurance Company® or COUNTRY Preferred Insurance Company®, Bloomington, IL.
COUNTRY Financial® is a family of affiliated companies (collectively, COUNTRY) located in Bloomington, IL. Learn more about who we are.
We take pride in providing accurate, truthful information in our articles. See our editorial standards to learn more.
These are examples and used for illustrative purposes only. Not all physical damages losses are covered. Coverage is subject to policy terms, conditions, and exclusions.
The descriptions provided are for general informational purposes only and are not intended to constitute an insurance policy or to modify, amend or extend the terms, conditions or coverages of any insurance policy. Coverage, terms, limitations and exclusions vary. For complete details, please refer to the applicable insurance policy or contact a COUNTRY Financial representative.